

What Does Total Return Actually Measure?
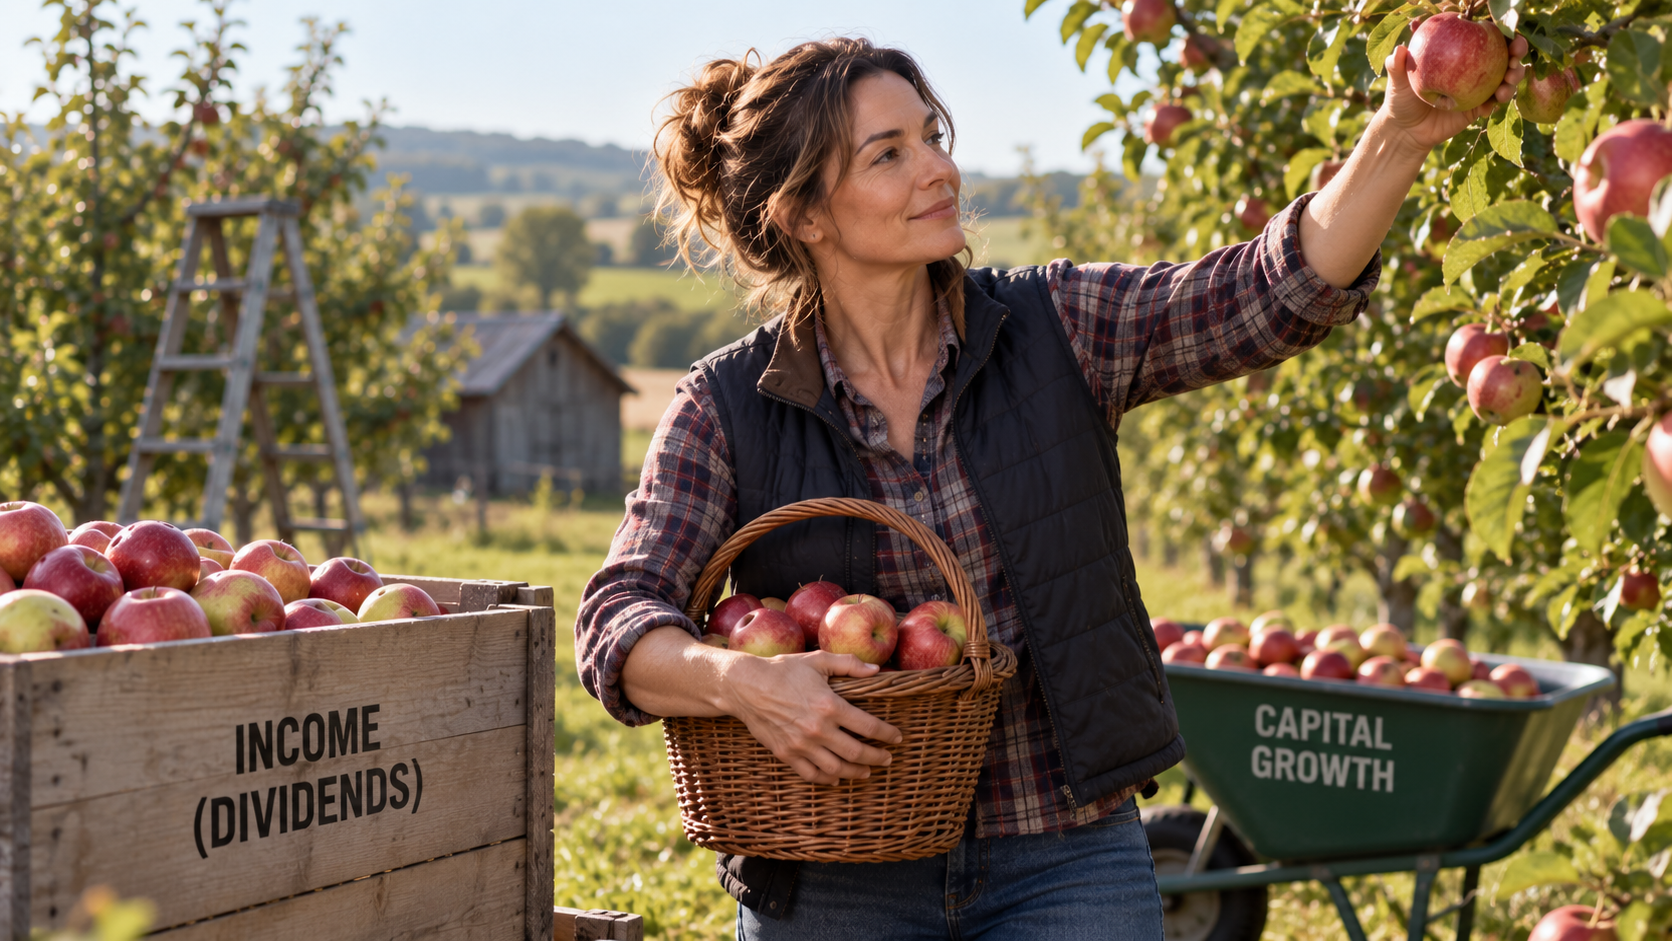
Total return measures the overall gain or loss produced by an investment over a particular period. It considers both the change in the investment’s value and any investment income produced during that period.
That makes total return broader than looking only at whether an investment’s market value has risen or fallen.
Suppose an investment starts at £10,000 and finishes the year worth £10,600. Its value has increased by £600.
If the investment also produced £300 of income during the year, looking only at the £600 increase would leave part of the return out. The investment has actually produced £900 through the combination of capital growth and income.
Change in Value
The investment rises from £10,000 to £10,600. That £600 increase represents capital growth and contributes to the overall return.
Investment Income
The investment also produces £300 of income, such as dividends or interest. This is another part of the return produced during the period.
Total return brings both sources together. In this example, £600 of capital growth plus £300 of investment income produces an overall gain of £900.
An investment does not need to produce both types of return. Some investments may increase in value without producing income, while others may generate income while their market value changes very little.
Total return simply asks a broader question:
What did the investment return overall once both the change in value and the income it produced are considered?
This builds on the distinction between capital growth and investment income. Those are different potential sources of investment return; total return provides a way of considering them together.
How Is Total Return Calculated?
The basic total return calculation combines the change in investment value with any investment income and compares the result with the investment’s starting value.
The formula is:
Total return = (Ending value − Starting value + Investment income) ÷ Starting value × 100
Suppose an investment:
- starts at £10,000;
- finishes at £10,600; and
- produces £300 of investment income.
The calculation brings both parts of the return together.
This example shows how capital growth and investment income combine to produce the investment’s total return. The investment has increased in value by £600. Adding the £300 of income means the investment produced an overall gain of £900. The overall £900 gain is compared with the £10,000 starting value. Multiplying by 100 converts the result into a percentage.
Calculating Total Return
The investment’s total return is therefore 9%.
If the £300 of income were ignored, the increase from £10,000 to £10,600 would show only a 6% change in value. That figure is not incorrect; it is simply measuring something narrower.
Total return includes the additional income produced during the same period.
If you want to revisit how a monetary gain or loss is converted into a percentage, How Are Investment Returns Calculated? explains the underlying calculation. You can also use the Investment Return Calculator to explore how different starting and ending values affect an investment return.
Total Return vs Capital Growth
Capital growth and total return are related, but they answer different questions.
Capital growth measures how much an investment’s value increased or decreased.
Total return looks more broadly at what the investment produced by including investment income alongside that change in value.
Using the same £10,000 investment makes the difference clear.
The same investment can produce different return figures depending on whether investment income is included. This measures only the £600 increase in the investment’s value. This includes both the £600 increase in value and the £300 of income produced during the period. Capital growth measures the change in the investment’s value. Total return adds the income produced during the period, increasing the measured return from 6% to 9% in this example.Capital Growth vs Total Return
Change in investment value
Change in value plus income
Neither figure is inherently wrong. What matters is understanding what the percentage is intended to measure.
If you specifically want to know how an investment’s market value changed, the capital-growth figure provides that information. If you want to consider the broader return produced by both value changes and income, total return is more appropriate.
The distinction can be particularly important for investments where income forms a meaningful part of the overall return. Looking only at price movement can leave that income out of the comparison.
How Do Dividends Affect Total Return?
Dividends are one form of investment income and can therefore contribute to total return.
Suppose shares start the year worth £10,000 and finish worth £10,500.
The £500 increase represents a 5% gain in value.
If the shares also produced £250 of dividends during the year, those dividends are another part of the return. The combined gain would be:
£500 capital growth + £250 dividends = £750
Relative to the original £10,000 investment, that represents a 7.5% total return.
The dividend has not changed the £500 capital gain. Instead, it has added another source of return alongside it.
Dividends can form part of the return whether they are taken as cash or reinvested. Reinvestment affects what happens to that income afterwards rather than whether the original dividend was produced.
What Are Dividends and How Do They Work? explains dividend payments in more detail.
Can Total Return Be Negative Even If You Receive Income?
Yes. Receiving investment income does not automatically mean an investment produced a positive total return.
If an investment falls in value by more than the income it produces, its overall return can still be negative.
The £300 income is still a positive part of the return. It simply was not large enough to offset the £800 decline in value.
The reverse is also possible. An investment could fall slightly in value but produce enough income to outweigh the decline, resulting in a positive total return.
This is why income alone does not tell you whether an investment gained or lost overall.
Total return depends on the combined effect of the change in value and the income produced.
Does Reinvesting Income Change the Return?
Total return and reinvestment are related ideas, but they are not the same thing.
Suppose an investment produces £300 of dividend income.
If you take the £300 as cash, you have received £300 of investment income.
If you reinvest it, the same £300 is instead used to increase your investment holding. Reinvesting it does not turn the original £300 into another £300 of immediate return.
The difference appears in what can happen afterwards.
Additional investments purchased using reinvested income can themselves rise or fall in value and may produce further income. Repeated reinvestment can therefore affect how the investment develops over longer periods.
A useful distinction is:
Total return measures what the investment produced. Reinvestment describes what happens to the income after it is produced.
When looking at published historical return figures, it is also important to check how distributions have been treated. Return figures may be calculated on different bases, including assumptions about whether distributions are reinvested, so apparently similar percentages may not always be directly comparable.
What Is Dividend Reinvestment? explains the process in more detail, while the Dividend Reinvestment Calculator can show how reinvested dividends may affect an investment over time under different assumptions.
Why Is Total Return Useful When Comparing Investments?
Total return can make comparisons more meaningful when investments produce different combinations of capital growth and income.
Consider two investments that each start at £10,000.
Investment A finishes the year worth £10,800 and produces no income.
Investment B finishes worth £10,500 but also produces £400 of investment income.
Looking only at the change in market value would make Investment A appear to have produced the larger return. Including income changes the comparison.
Looking at capital growth alone can produce a different comparison from looking at the complete return. Investment A gained £800 in value and produced no additional income. Investment B gained less in value, but the £400 of income increased its overall return. Looking only at capital growth would make Investment A appear to have performed better: 8% compared with 5%. Once income is included, Investment B has the higher total return at 9%.Comparing Investments Using Total Return
Higher capital growth
Growth plus income
This does not mean Investment B is automatically the better investment.
Total return tells you about performance over the period being measured. It does not tell you how much risk was involved, how much either investment fluctuated or what either investment will return in the future.
Comparisons also need to use a consistent basis.
If one percentage includes investment income while another measures price movement only, they are not directly measuring the same thing. The periods being compared should also be consistent.
Total return therefore provides a broader performance comparison, rather than a complete assessment of an investment.
What Does Total Return Not Tell You?
Total return tells you how much an investment gained or lost overall during a defined period, but a single percentage cannot describe everything about the investment.
It does not show how the investment behaved between its starting and ending values. Two investments could produce the same total return while one experienced much larger changes in value along the way.
Total return also does not measure investment risk or volatility. A 10% total return tells you the outcome over the measured period, not how uncertain that outcome was or how much the investment’s value fluctuated while producing it.
It does not automatically adjust for inflation either. If a quoted return is nominal, rising prices will affect how much purchasing power the investment actually gained. Nominal vs Real Returns explains this distinction.
The length of the measurement period also matters. A 20% total return accumulated over five years is not directly equivalent to a 20% return achieved over one year. What Is an Annualised Return? explains how a multi-year result can be converted into an equivalent compounded yearly rate.
Finally, total return is a measurement of performance that has already occurred. A strong historical total return does not establish what an investment will return next. Why Past Performance Does Not Guarantee Future Returns explains why historical results should not be treated as predictions.
Total return is therefore most useful when you are clear about what is included, what period is being measured and what the figure does not attempt to tell you.
Conclusion
Total return measures the overall gain or loss produced by an investment over a particular period by bringing together two potential sources of return:
the change in the investment’s value + investment income.
If £10,000 grows to £10,600 and also produces £300 of income, the investment has generated a £900 overall gain, equivalent to a 9% total return.
Looking only at the change in value would show 6%. That figure measures the capital growth correctly, but it leaves the investment income out.
Total return can also be negative even when income is received if a fall in investment value is larger than the income produced. Equally, an investment with relatively modest capital growth can produce a stronger overall return when income is included.
This makes total return useful when comparing investments that generate different combinations of growth and income, provided the figures cover comparable periods and are calculated on a consistent basis.
Capital growth tells you how the investment’s value changed. Total return gives the broader picture by considering that change alongside the income the investment produced.


