

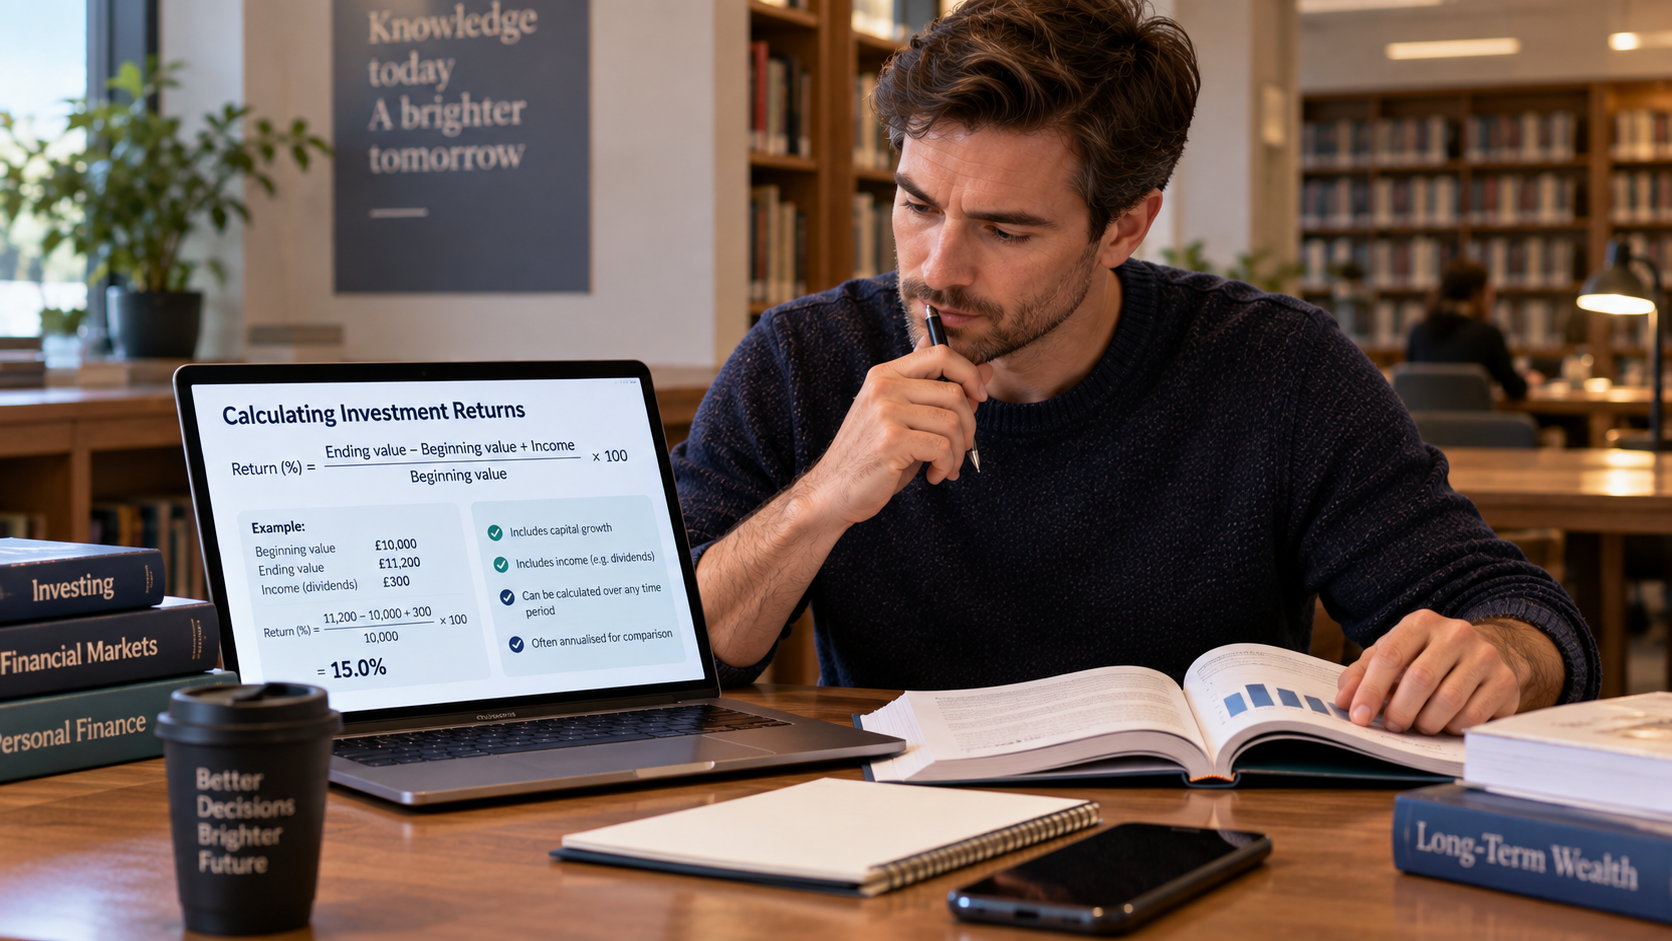
What Do You Need to Calculate an Investment Return?
A simple investment return calculation measures how much an investment gained or lost relative to its starting value.
To calculate it, you need three pieces of information:
- the starting value of the investment;
- the ending value of the investment; and
- the period being measured.
Suppose an investment is worth £20,000 at the beginning of a year and £21,500 at the end.
The investment has increased by £1,500. Comparing that £1,500 gain with the original £20,000 tells you how large the gain was relative to the amount you started with.
The period matters because it tells you what the result represents. If £20,000 becomes £21,500 over one year, the percentage describes the return over that year. If the same change happens over three years, the percentage change is the same, but it describes the return across the complete three-year period.
This simple calculation works best when you are comparing an investment at two points in time and there have been no additional cash flows that need to be accounted for. We will look later at what happens when income, contributions or withdrawals are involved.
How Is an Investment Return Calculated?
The basic investment return formula compares the gain or loss with the amount the investment was worth at the beginning of the period.
The formula is:
Investment return = (Ending value − Starting value) ÷ Starting value × 100
Suppose an investment starts at £10,000 and finishes the year worth £10,800.
This example shows how an increase from £10,000 to £10,800 becomes an 8% investment return. The investment has increased in value by £800. The £800 gain is equal to 0.08 of the original £10,000 investment. Multiplying by 100 converts the decimal result into a percentage.
Calculating an 8% Investment Return
The investment has therefore produced an £800 monetary gain and an 8% investment return over the period.
These are two ways of describing the same change. The £800 tells you how much the investment gained, while the 8% tells you how large that gain was relative to the amount you started with.
If you want to apply the calculation to different figures, the Investment Return Calculator can show the monetary change alongside the percentage return.
How Does the Same Formula Work for a Loss?
You do not need a different formula when an investment falls in value.
If the ending value is lower than the starting value, subtracting the starting value produces a negative number. That negative change then produces a negative percentage return.
Positive Return
An investment rises from £10,000 to £10,800. The £800 gain divided by the £10,000 starting value produces a return of +8%.
Negative Return
An investment falls from £10,000 to £9,200. The £800 loss divided by the £10,000 starting value produces a return of −8%.
The calculation is the same in both cases. A higher ending value produces a positive return, while a lower ending value produces a negative return.
The plus or minus sign therefore tells you the direction of the change.
A return of +8% means the investment increased by 8% relative to its starting value.
A return of −8% means it decreased by 8% relative to its starting value.
The calculation itself does not explain why the investment rose or fell, nor what that result might mean in a wider investment context. Positive vs Negative Investment Returns looks more closely at how those figures should be interpreted.
Why Is the Return Divided by the Starting Value?
The starting value provides the reference point for the return.
An £800 gain does not have one fixed percentage value. Its significance depends on how much the investment was worth at the beginning.
Consider two investments that both gain £800.
The first starts at £10,000:
£800 ÷ £10,000 × 100 = 8%
The second starts at £20,000:
£800 ÷ £20,000 × 100 = 4%
Both investments have made exactly the same £800 monetary gain, but they have not produced the same percentage return.
The first investment gained 8% relative to its starting value, while the second gained 4%.
This illustrates the difference between a monetary return and a percentage return.
Monetary return tells you how much money the investment gained or lost.
Percentage return tells you how large that gain or loss was relative to the starting investment.
This is one reason percentage returns are useful when comparing investments of different sizes.
A £1,000 gain on a £10,000 investment represents a 10% return. The same £1,000 gain on a £50,000 investment represents only 2%.
Using the ending value as the denominator would answer a different question. For a basic investment return, you want to know how much the investment changed compared with where it started, so the starting value is used as the reference point.
If you want to step back from the calculation and look at what a return represents more generally, What Is an Investment Return? explains the underlying concept.
When Is the Simple Return Formula Not Enough?
Comparing starting and ending values works well when those two figures capture the investment performance you are trying to measure.
However, other movements of money can make the situation more complicated.
Suppose an investment starts at £10,000 and finishes at £10,500. Looking only at those two values suggests a £500 increase.
But what if the investment also paid £300 of dividends during the period?
That income is part of what the investment produced, even though it may not be included in the £10,500 ending value.
Contributions create a different issue. If you add £2,000 to an investment during the year, some of the increase in the ending balance came from your own additional money rather than investment performance.
Withdrawals can have the opposite effect. Taking money out can reduce the ending value without necessarily meaning the investment itself produced an equivalent loss.
Comparing starting and ending values works well for a simple change in investment value. Other cash flows may need to be considered before the result can accurately describe investment performance. There is a clear value for the investment at the beginning of the period. There is a clear value for the investment at the end of the same period. No contributions, withdrawals or separately received investment income need to be accounted for during the period. Dividends, interest or other income received separately may form part of the return even though they are not included in the ending investment value. Contributions can increase the ending value without representing an investment gain. Withdrawals can reduce the ending value even though the reduction was caused by money being taken out rather than investment performance. Fees, taxes and other movements of money can affect what a particular return figure represents and may need separate consideration depending on what you are trying to measure. Starting and ending values are enough for a simple percentage-change calculation, but they are not always enough to measure the complete return received from an investment.When the Simple Return Formula Is — and Isn't — Enough
The simple calculation works well when
A broader calculation may be needed when
This does not make the basic investment return formula wrong. It means you need to understand what the result is measuring.
A simple starting-to-ending calculation measures the change in investment value relative to where it started. If you want a broader measure that also includes investment income, What Is Total Return? explains how income and changes in value can be considered together.
Contributions and withdrawals need particular care because they represent money moving into or out of the investment rather than returns generated by the investment itself.
The important principle is not to assume that every difference between a starting and ending account balance represents investment performance.
Does the Time Period Change the Calculation?
The length of the investment period does not change the basic return formula, but it does change what the resulting percentage means.
Suppose an investment increases from £10,000 to £12,000.
The basic calculation is:
(£12,000 − £10,000) ÷ £10,000 × 100 = 20%
If that increase occurred over one year, the investment produced a 20% return over one year.
If exactly the same increase occurred over five years, the calculation would still produce a 20% total change, but that percentage would now describe the complete five-year period.
It would not mean the investment returned 20% every year.
This is why the measurement period should always be considered alongside a return percentage. A return figure without a time period can leave important information unclear.
A multi-year return also cannot generally be converted into an equivalent yearly return simply by dividing the percentage by the number of years. Compounding needs to be taken into account.
When you want to express multi-year investment performance as an equivalent compounded yearly rate, What Is an Annualised Return? explains the separate calculation.
For the basic investment return formula, the distinction is simpler:
The percentage tells you the overall gain or loss between the starting and ending values. The period tells you how long it took for that change to occur.
Conclusion
A simple investment return calculation measures how much an investment gained or lost relative to its starting value.
The basic formula is:
Investment return = (Ending value − Starting value) ÷ Starting value × 100
If £10,000 becomes £10,800, the investment has gained £800. Comparing that gain with the £10,000 starting value gives an investment return of 8%.
The same formula works for losses. If the ending value is below the starting value, the change is negative and the resulting percentage return is negative.
Using a percentage also provides context that a monetary gain or loss alone cannot. The same £800 gain represents an 8% return on £10,000 but only a 4% return on £20,000.
The basic formula is most straightforward when no additional money has moved into or out of the investment during the period. Investment income, contributions and withdrawals can change what a simple starting-to-ending comparison represents and may require a broader approach.
The time period matters too. A return percentage describes the change across the period being measured; it should not automatically be interpreted as an annual return.
The calculation tells you how large the investment’s gain or loss was relative to where it started. Understanding the figures and the period behind that percentage tells you what the return actually represents.


