Start With Why the Savings Were Spent
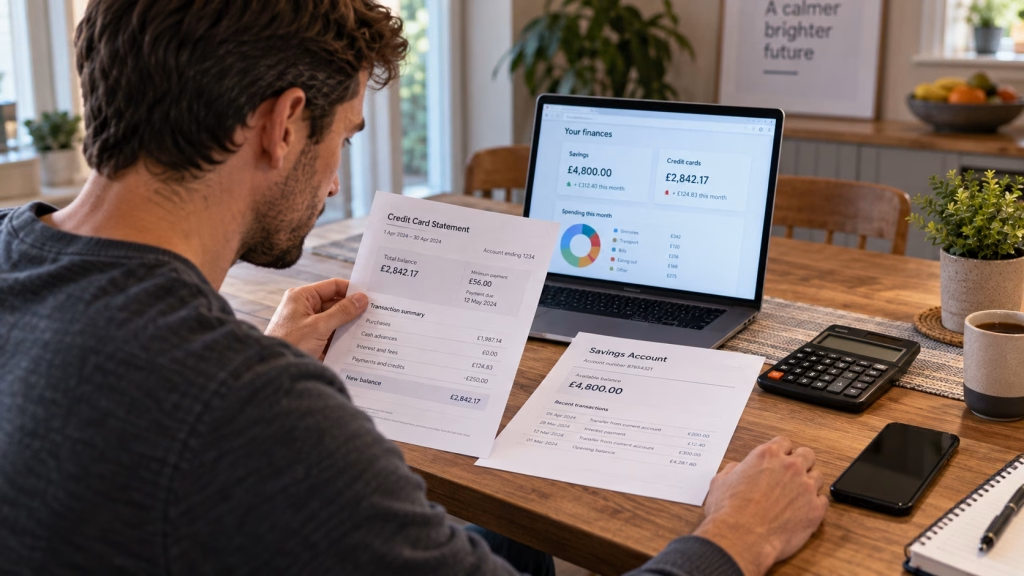
If your savings balance has fallen substantially or disappeared altogether, it can feel as though you have gone backwards. But spending savings does not necessarily mean that something went wrong.
Savings exist to be used. If you built up money for a house repair, holiday, car or another planned expense and then paid for it, the savings achieved their purpose. Similarly, an emergency fund that helped you deal with an unexpected expense or a temporary loss of income did what it was designed to do.
The starting point is therefore not simply to replace everything you spent. First, understand why the money was used and whether that changes what you now need to save for.
Why did your savings fall?
The reason you spent the money can affect what you need to do next. A lower savings balance does not always mean the same thing.
You reached a planned goal
If the money paid for something you deliberately saved towards, that part of your savings may not need to be replaced unless you now have another goal.
You dealt with an emergency
If emergency savings absorbed an unexpected financial shock, rebuilding some of that protection may now become a priority.
Your income or circumstances changed
Savings may have helped cover essential spending during a period of lower income or higher costs. Your current budget may now support a different saving amount from before.
The money gradually went on everyday spending
If savings were repeatedly transferred back into your current account, it can be useful to understand what was putting pressure on your monthly budget before restarting.
These situations can overlap. You might have used part of your savings for its intended purpose and another part to deal with an unexpected cost. What matters is separating those different jobs before deciding what needs rebuilding.
Work Out What You Actually Need to Rebuild
Your previous savings balance is not automatically your new target. Some of the money may have been accumulated specifically so that it could eventually be spent.
Instead of concentrating on the amount that has disappeared from the account, look at the financial jobs that still need funding. You may need to replenish emergency savings, prepare for known upcoming expenses or continue working towards a goal that has not yet been reached.
This distinction is particularly useful when several purposes are combined within one savings account. A falling account balance can look like lost progress even when part of that money was always intended to be spent.
If you are unsure how much accessible money still has a useful purpose, How Much Money Should You Keep in Savings? looks at emergency resilience, known upcoming costs and shorter-term goals separately.
If it was specifically your emergency fund that was depleted, the amount worth rebuilding depends on your essential spending and wider circumstances rather than the balance you happened to have before. How Much Emergency Savings Should You Have? explores that question in more detail.
Check What Your Budget Can Support Now
Once you know what needs rebuilding, the next question is how much you can realistically start putting aside again.
Your finances may not look the same as they did when you originally built the savings. Essential costs could have increased, your income might have changed or the event that caused you to use the money may still be affecting your budget.
For that reason, simply restarting your previous monthly contribution may not be appropriate. If you used to save £300 a month but that amount would now leave too little money for essential spending, forcing yourself back to £300 could make the new plan difficult to maintain.
Look at what remains after your main commitments and realistic everyday spending. The amount you can repeatedly afford is generally more useful than a larger contribution that regularly has to be withdrawn again.
Restart With an Amount You Can Keep Going
Starting again does not have to mean rebuilding your savings as quickly as possible. A smaller regular contribution can be enough to re-establish the habit and begin moving the balance in the right direction.
If £50 a month is currently manageable, for example, there is little benefit in deciding that you must save £200 if doing so repeatedly leaves you short before the next payday. You can increase the contribution later if your finances allow.
This is also why the amount you previously saved should not become a target you feel obliged to match immediately. Your old contribution reflected your finances at that time. Your new contribution needs to work with your finances now.
If you want to reassess the amount rather than simply returning to your previous figure, How Much Should You Save Each Month? explains how affordability, goals and timescale can help you think about a sustainable contribution.
Make the Restart Automatic Where It Helps
Once you have chosen an amount, making the transfer happen automatically can remove one of the decisions involved in starting again.
A standing order shortly after payday can move the money into savings before it becomes mixed with the amount available for everyday spending. This does not make the contribution compulsory — you can still change it when your circumstances change — but it can make regular saving easier to maintain.
Keeping savings separate from your everyday spending money can also make their purpose clearer. This can be particularly useful if your previous savings gradually disappeared through small transfers back into your current account.
Automation is a tool rather than a solution by itself. If the contribution is unaffordable, automatically transferring it will not fix the underlying problem. How to Save Money Automatically explains the different ways regular saving can be set up once you have decided what you can afford.
Rebuild the Most Important Savings First
If several parts of your savings were spent, you do not necessarily need to rebuild all of them at the same speed.
Some savings may provide basic financial resilience, while others relate to goals with flexible deadlines. Money needed for an approaching unavoidable expense may also deserve attention before money intended for something that could easily be postponed.
For example, rebuilding some accessible emergency savings may currently matter more than restarting contributions towards a discretionary purchase several years away. In another situation, an unavoidable expense with a firm deadline might need to be funded first.
The purpose is not to create a rigid order that applies to everyone. It is to decide which missing savings would create the greatest problem if they were not rebuilt. How to Decide What to Save for First looks more closely at prioritising competing savings goals using urgency, consequences and timescale.
If You Keep Needing to Use Your Savings, Look at Why
Occasionally withdrawing savings is not necessarily a problem. The whole point of having accessible savings is that the money can be used when its intended purpose arrives.
Repeatedly moving money into savings and then taking it back out to cover ordinary spending is different. If this happens frequently, the useful question is not simply how to stop yourself withdrawing the money. It is why your normal budget keeps needing it.
If predictable expenses are causing the problem, separating them from genuine emergencies can help. A known annual insurance bill or expected car service, for example, is different from an unexpected breakdown. Money set aside gradually for predictable future costs is often described as a sinking fund.
Planning for those costs separately can make it easier to see whether your emergency savings are genuinely being depleted or whether ordinary but irregular spending is simply missing from your monthly budget.
A Simple Plan for Starting Again
You do not need to restore your previous balance immediately. A structured restart can help you establish what needs rebuilding and make progress at a pace your current finances can support.
The first few contributions may seem small compared with the amount you previously had saved. That does not make them insignificant. Their immediate job is to restart progress and establish a saving level that does not repeatedly put pressure on the rest of your budget.
Increase the Amount When Your Budget Allows
Your initial saving amount does not have to remain fixed. Once you have been saving again for a while, you can review whether your budget comfortably supports a higher contribution.
An increase in income, the end of a regular expense or paying off a debt could create additional capacity. You may also find that the amount you chose when restarting was deliberately cautious and that a modest increase is now manageable.
There is no need to wait for a major financial change. Even relatively small increases to a regular contribution can add up when they continue over many months.
The opposite is also true. If circumstances become more difficult, reducing the contribution temporarily can be more practical than maintaining an amount that repeatedly forces you to take money back out of savings.
Rebuilding is therefore not a race back to an old account balance. The aim is to create a saving pattern that works with your current finances and gradually restores the financial protection or goals that still matter.
Conclusion
Spending your savings does not automatically mean that your saving plan failed. If the money paid for the purpose you originally saved it for, using it may have been the successful end of that particular goal.
When savings do need rebuilding, start by deciding what actually needs replacing and what your current budget can afford. Prioritise the savings that matter most, choose a contribution you can maintain and make it regular where that helps.
You can increase the amount later as your finances improve. Starting again with a sustainable plan is more useful than trying to restore your previous balance immediately and finding that the new contribution does not work with your life today.