Why the decision to fix your savings has changed
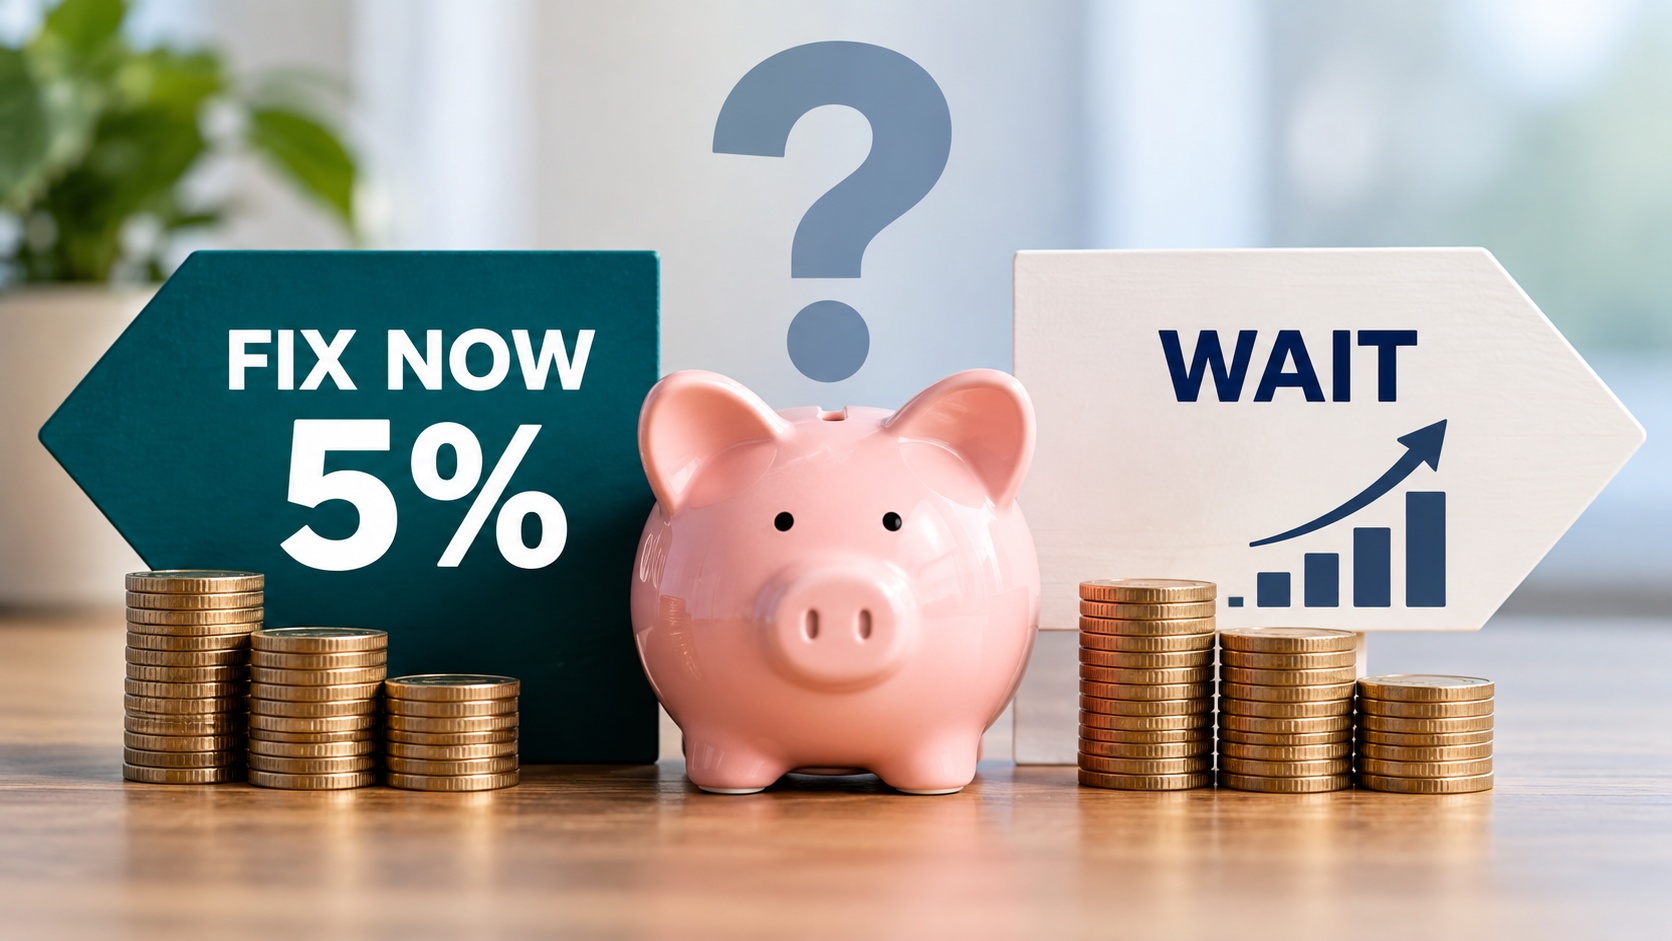
Fixed savings rates have climbed above 5% again, leaving savers with a decision that looked much less likely only a few months ago: secure one of today’s rates, or wait to see whether rates rise further.
The question has become more relevant because the outlook for UK interest rates has changed. The Bank of England kept Bank Rate at 3.75% in September, but three members of its Monetary Policy Committee voted to increase it to 4%. Market interest rates have also moved higher as concerns about inflation have increased.
That does not mean savings rates are certain to keep rising. Fixing now offers certainty, while waiting preserves the possibility of finding a higher rate later. Each choice involves giving something up, which means the headline rate is only one part of the decision.
Why are savers considering fixing at 5% now?
Fixed savings rates have strengthened during September. Moneyfacts reported that average one-year fixed savings rates rose from 4.23% at the beginning of August to 4.28% at the beginning of September, while longer-term fixed rates reached their highest average level in more than two years.
Some of the leading individual accounts have moved considerably higher than those market averages, with fixed rates above 5% available during September. That creates a different decision for savers from simply looking for the highest rate available today.
The question is whether to secure one of those rates while it is available or retain flexibility in case the savings market moves higher.
The backdrop matters. At its September meeting, the Bank of England voted by six to three to keep Bank Rate at 3.75%, with the other three members preferring an immediate increase to 4%. The Bank also said risks to the inflation outlook had moved further to the upside.
Financial markets have responded to that uncertainty. The Bank reported that short-term market interest rates had risen and that the perceived probability of a near-term increase in Bank Rate had increased.
This has helped create conditions in which savings providers can offer higher fixed rates even though Bank Rate itself has not changed. We explain that relationship in more detail in Why Are Savings Rates Rising Again When Bank Rate Hasn’t Changed?.
What do you actually get by fixing your savings now?
A fixed-rate savings account normally pays an agreed interest rate for a set period. Depending on the account, that might be one year, two years, three years or considerably longer.
The main benefit is certainty. If you put money into a fixed-rate account paying 5% AER and meet the account conditions, a later fall in savings rates would not normally reduce the agreed rate during the fixed term.
The trade-off is flexibility. Fixed accounts commonly restrict withdrawals during the term, and some do not permit access at all except in particular circumstances. There may also be a limited period in which you can initially fund the account.
Our guide to fixed-rate savings accounts explains how these accounts work, including access restrictions, interest and what happens when the fixed term ends.
Fixing therefore does more than secure an interest rate. It also means accepting the account’s conditions for the period involved.
What could happen if you wait for rates to rise further?
Waiting keeps your options open. If fixed rates continue rising, a saver who has not already locked their money away may be able to secure a higher rate later.
But the possibility of higher rates is not the same as knowing that higher rates will become available.
The Bank of England has made clear that the future path of monetary policy depends on how inflation develops. Its September decision showed disagreement within the Monetary Policy Committee, while the Bank also described considerable uncertainty around energy prices and their effect on inflation.
There are therefore several possible outcomes. Savings rates could rise further, remain around current levels or move lower if the economic and interest-rate outlook changes.
A saver who waits is effectively retaining flexibility in exchange for accepting that uncertainty. If rates rise, waiting may provide access to better deals. If rates fall, some of the fixed rates available today may no longer be available.
Fix now
You can secure the available rate for the chosen term, giving you certainty about the interest rate. In return, you normally accept restrictions on accessing the money and may be unable to benefit if substantially higher fixed rates become available later.
Wait
You retain flexibility and may be able to take advantage if fixed rates rise further. However, future rates are uncertain, and the rates available today could also fall or disappear.
Neither choice removes uncertainty entirely. Fixing gives certainty over the rate but reduces flexibility, while waiting preserves flexibility but leaves the future rate unknown.
Would a Bank Rate rise automatically push savings rates higher?
Not necessarily. Bank Rate influences savings rates, but savings providers do not simply add or subtract every Bank of England change from the rates they offer customers.
Providers also consider their own funding requirements, competition for savers’ money and expectations for market interest rates. This is particularly important for fixed accounts because a provider is agreeing today to pay a particular rate for a future period.
That means some anticipated changes in Bank Rate can already be reflected in fixed savings rates before the Bank of England makes a decision.
It also means that an eventual increase in Bank Rate would not guarantee that a particular one-year, two-year or five-year savings rate would increase by the same amount. The savings market may have moved in anticipation beforehand.
For somebody deciding whether to fix, this distinction matters. Waiting for Bank Rate itself to rise is not necessarily the same as waiting for fixed savings rates to rise.
Does the length of the fixed term matter?
A 5% rate does not mean the same thing when comparing accounts with very different fixed periods.
A one-year account commits the money for a relatively short period. A five-year account could secure a similar rate for much longer, but it also means accepting the account’s restrictions for several additional years.
Longer fixes can therefore provide more certainty about the rate earned over time, but they also increase the period during which a saver may be unable to respond to changing rates or changing personal circumstances.
This is why comparing fixed accounts purely by their headline AER can miss an important part of the decision. The rate and the period for which it is fixed need to be considered together.
How important is access to your savings?
Whether you may need the money during the fixed term can be just as important as the interest rate.
Money intended for an emergency fund, an approaching purchase or another short-term need may have a different role from savings that are unlikely to be required for several years. A higher fixed rate may be less useful if securing it means locking away money that needs to remain accessible.
Easy-access accounts generally provide greater flexibility, although their rates can change. Fixed accounts generally provide greater certainty over the rate, but at the cost of access.
Our comparison of easy-access and fixed-rate savings looks at those differences in more detail.
The purpose of the money matters too. Someone saving for an expense due within a known period may think about access differently from someone building savings without a fixed spending date. Our guide to choosing a savings account for your goal explains how the intended use of the money can help narrow the account types worth considering.
Do you have to choose between fixing everything and waiting?
The decision does not necessarily have to apply to an entire savings balance.
Savings can be held across different accounts for different purposes. For example, part of a balance might need to remain accessible while another part is unlikely to be required during a fixed term.
Splitting savings in this way does not remove the uncertainty over future rates. Instead, it changes how much of the balance is exposed to each trade-off. Money held in a fixed account has rate certainty but less flexibility, while money remaining accessible can potentially respond to future rate changes.
Whether that structure is useful depends on what the money is for and how much access is required. Our guide to splitting savings between different accounts explores the reasons someone might use more than one type of savings account.
What should you compare before deciding whether to fix?
The headline interest rate is an obvious starting point, but it should not be the only comparison.
The length of the fixed term determines how long the rate applies and how long the money may be restricted. Withdrawal conditions determine whether early access is possible and whether any penalty applies. Minimum and maximum deposits can affect whether an account is suitable for the amount being saved.
It is also worth checking how and when interest is paid, whether additional deposits are allowed after the account is opened and what happens when the fixed term reaches maturity.
These details can make two accounts paying similar headline rates work quite differently in practice. How to Compare Savings Accounts Properly explains the wider factors that can be considered alongside AER when comparing accounts.
What don’t we know about where savings rates go next?
The most important unknown is the future path of interest rates.
The Bank of England’s September meeting provides evidence that policymakers are concerned about inflation. Three Monetary Policy Committee members wanted Bank Rate increased immediately, while the majority preferred to leave it unchanged and continue assessing the evidence.
Financial-market pricing has also moved towards higher interest rates, but market expectations can change quickly as new information emerges. They are not a promise about what the Bank of England will do.
The next scheduled Monetary Policy Committee decision is on 5 November 2026. Between now and then, inflation, economic activity, the labour market, energy prices and financial-market conditions could all affect expectations.
Even knowing the eventual Bank Rate decision would not tell us exactly what individual savings providers will do. Providers can change their products and rates independently according to their own funding requirements and competitive position.
That is why today’s choice cannot be reduced to predicting whether Bank Rate will rise. The decision is between the certainty and restrictions available now and the flexibility and uncertainty involved in waiting.
Conclusion
Fixed savings rates above 5% have created a genuine decision for savers. Fixing can secure a known rate for a defined period, while waiting preserves the opportunity to respond if rates move higher.
Neither option guarantees the better outcome. Rates could rise further, but they could also stabilise or fall, and changes in Bank Rate do not translate mechanically into equivalent changes in fixed savings rates.
The more useful comparison is therefore not simply 5% today against a possible higher rate tomorrow. It is the certainty of the rate, the length of the commitment, access to the money and the purpose of the savings. Those factors determine what is being gained — and what is being given up — by fixing now rather than waiting.
Research transparency Sources, Limitations & Methodology See how this research was carried out, what data was used and what the findings cannot tell us.
Methodology
This article uses the Bank of England’s September 2026 Monetary Policy Summary and Minutes to establish the current Bank Rate, the Monetary Policy Committee vote and the Bank’s assessment of the inflation and interest-rate outlook. Current Moneyfacts savings-market evidence is used to establish that fixed savings rates strengthened during September and that fixed rates above 5% have been available. The article compares the practical implications of fixing at current rates with retaining flexibility to respond to future rate changes. It does not attempt to forecast Bank Rate or identify which option will produce the highest return.
Limitations
Savings products and interest rates can change at short notice, so rates available after the reference date may differ from those discussed here. Market expectations for future interest rates are not forecasts or guarantees of future Bank of England decisions. An eventual change in Bank Rate would not necessarily produce an equivalent change in individual savings rates. Account access, deposit and maturity conditions also vary between providers, so the article explains the decision in general terms rather than assessing individual savings products.

